Fixed vs. Variable Rate Mortgages: Understanding the Payment Differences
Choosing between a fixed-rate and variable-rate mortgage is a significant decision for any homebuyer in Quebec. Understanding the difference in payment structures is crucial for budgeting and financial planning.
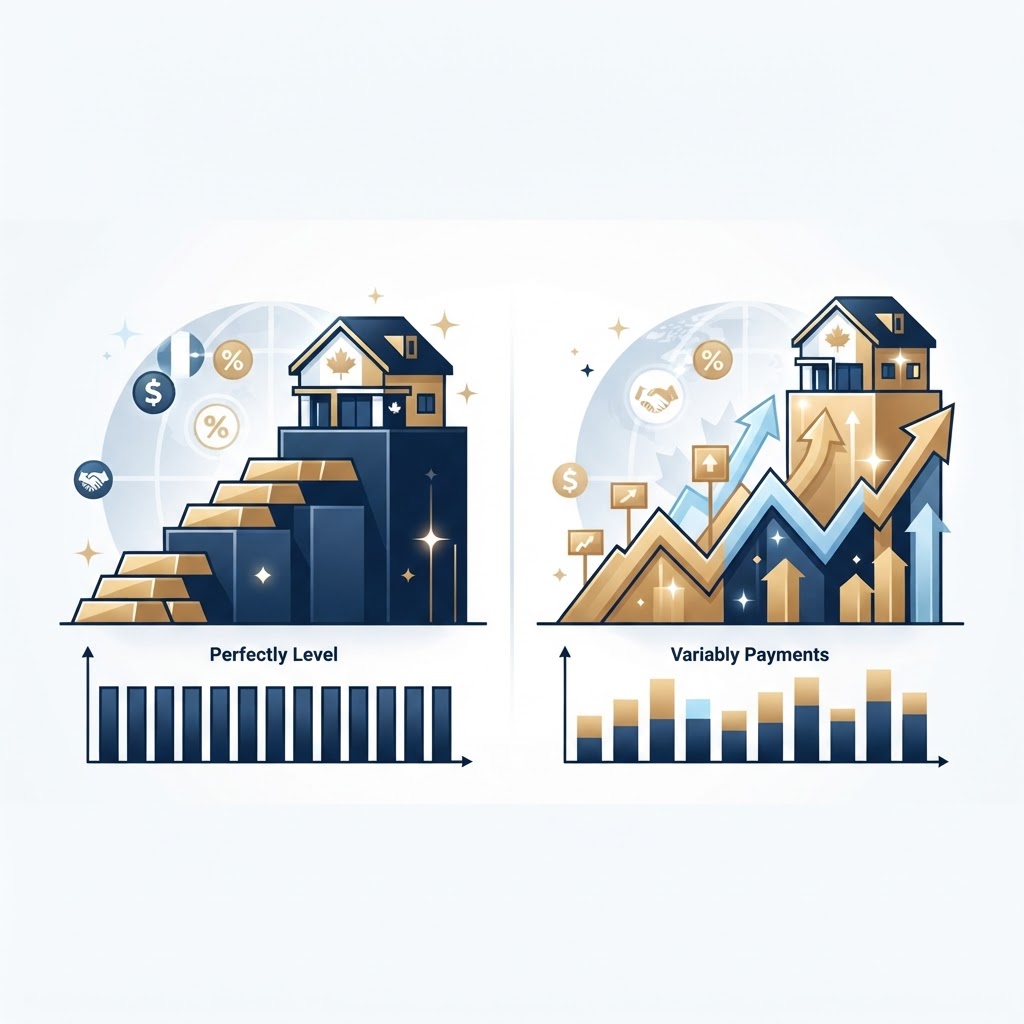
Understanding the Core Differences: Fixed vs. Variable Rate Mortgages
When embarking on the journey of homeownership in Quebec, one of the most pivotal decisions you'll make is selecting the right mortgage. Two primary options dominate the landscape: fixed-rate mortgages and variable-rate mortgages. While both serve the fundamental purpose of financing your home, the critical distinction lies in how their interest rates and, consequently, their payment structures behave over time. This article delves into the nuances of the difference between fixed and variable rate mortgage payments, empowering you to make an informed decision aligned with your financial goals and risk tolerance.
Fixed-Rate Mortgages: The Predictability Advantage
A fixed-rate mortgage, as its name suggests, locks in your interest rate for the entire duration of your mortgage term, typically ranging from six months to ten years. This means that your monthly principal and interest payments remain constant, providing a high degree of certainty and stability in your budget.
Key Characteristics of Fixed-Rate Mortgages:
- Constant Payments: Your monthly payment amount will not change, regardless of fluctuations in market interest rates.
- Budgeting Ease: The predictability allows for straightforward financial planning and budgeting.
- Protection from Rate Hikes: You are shielded from potential increases in market interest rates during your term.
Example Scenario (Hypothetical):
Let's consider a hypothetical mortgage of $500,000 with a 5-year fixed interest rate of 5.00%, an amortization period of 25 years, and a down payment of 20%. As of October 2, 2026, such a rate might be achievable, though actual rates vary.
- Mortgage Amount: $500,000
- Down Payment: 20% ($125,000 on a $625,000 home)
- Term: 5 years
- Amortization Period: 25 years
- Interest Rate: 5.00% (hypothetical rate for October 2, 2026)
Your estimated monthly principal and interest payment would be approximately $2,905.20. This payment would remain the same for the entire 5-year term. This calculation is an estimate and depends on the specific rates available and lender criteria at the time of application.
When a Fixed-Rate Mortgage Might Be Ideal:
- You have a strict budget and would be challenged by increasing mortgage payments.
- You prefer the peace of mind that comes with knowing your exact payment amount.
- You believe interest rates will rise and want to secure a lower rate now.
Variable-Rate Mortgages: The Potential for Savings and Risk
A variable-rate mortgage, also known as a floating-rate mortgage, has an interest rate that fluctuates over the term of your mortgage, typically tied to your lender's prime rate. This means your payment can increase or decrease based on market conditions.
Key Characteristics of Variable-Rate Mortgages:
- Fluctuating Rates: Your interest rate can change, usually monthly, as the prime rate shifts.
- Payment Variability: Depending on the mortgage structure (e.g., fixed payment or floating payment), your actual payment amount might change, or the allocation between principal and interest within a fixed payment will change.
- Potential for Savings: If interest rates fall, your payments could decrease, leading to potential long-term savings.
- Interest Rate Risk: You assume the risk that interest rates could rise, leading to higher payments or less principal being paid down.
How Payments Work with Variable Rates:
There are generally two main structures for variable-rate mortgages:
- Fixed Payment, Variable Rate: Your monthly payment amount remains constant. However, if interest rates rise, a larger portion of your payment goes towards interest, and less towards the principal. Conversely, if rates fall, more goes to the principal. This can lead to a longer amortization period if rates rise significantly, a concept known as negative amortization, or a shorter one if rates fall.
- Floating Payment, Variable Rate: Your monthly payment amount adjusts directly with changes in the prime rate. This means your payment will increase if rates rise and decrease if rates fall.
Example Scenario (Hypothetical):
Using the same mortgage details as above, but with a variable rate of Prime - 0.50%. As of October 2, 2026, the Bank of Canada's overnight rate is 2.25%, making the prime rate 4.45%. Thus, the variable rate would be 3.95%.
- Mortgage Amount: $500,000
- Down Payment: 20% ($125,000 on a $625,000 home)
- Term: 5 years
- Amortization Period: 25 years
- Interest Rate: 3.95% (Prime - 0.50%, based on Oct 2, 2026 prime rate of 4.45%)
Your estimated monthly principal and interest payment could be around $2,650.89. If the prime rate were to increase, say to 5.45% (Prime + 1.00%), your variable rate would become 4.95%. With a fixed-payment variable mortgage, your payment would likely stay at $2,650.89, but more would go to interest, and less to principal. If you had a floating payment, your payment would increase to approximately $3,125.17 to reflect the higher rate. These figures are estimates and subject to specific lender offerings and market conditions on October 2, 2026.
When a Variable-Rate Mortgage Might Be Ideal:
- You are comfortable with some level of risk and can manage potential payment increases.
- You anticipate interest rates will fall or remain stable.
- You want to take advantage of potentially lower initial rates.
The Impact on Your Payments: A Deeper Dive
The fundamental difference in mortgage payments between fixed and variable rates boils down to stability versus flexibility. With a fixed rate, your payment is a predictable constant. With a variable rate, the payment can shift, impacting your monthly budget.
Fixed Payments, Variable Rates
This is a common structure where your monthly payment amount stays the same. However, the proportion of that payment allocated to principal and interest changes with the prime rate.
- Rising Rates: More of your payment goes to interest, less to principal. This can extend your amortization period if the interest doesn't get fully covered, potentially leading to negative amortization. Lenders often have a 'trigger rate' where payments must be increased or a lump sum paid to prevent the amortization from extending indefinitely.
- Falling Rates: More of your payment goes to principal, less to interest. This accelerates your mortgage payoff.
Floating Payments, Variable Rates
In this structure, your monthly payment amount directly changes with the prime rate.
- Rising Rates: Your monthly payment increases.
- Falling Rates: Your monthly payment decreases.
This offers immediate adjustment but requires a more adaptable budget.
Key Considerations for Quebec Homebuyers
When choosing between fixed and variable rates in Quebec, consider the following:
- Your Risk Tolerance: Are you comfortable with the possibility of rising payments, or do you prioritize payment certainty?
- Budgetary Flexibility: Can your budget absorb potential increases in mortgage payments?
- Market Outlook: What are the current and forecasted interest rate trends in Canada? While predictions are uncertain, understanding economic indicators is crucial. For official data, visit the Bank of Canada.
- Mortgage Term: Shorter terms (e.g., 1-3 years) offer more frequent opportunities to adjust to changing rates, while longer terms (e.g., 5 years or more) provide greater rate stability within that period.
Quebec Mortgage Rates Context (as of October 2, 2026):
- 5-year Fixed: Approximately 4.59% to 5.09%.
- 5-year Variable: Approximately 3.45% to 4.16%.
It's important to note that these are indicative rates, and actual rates will vary based on the lender, your creditworthiness, and other factors. For instance, a $500,000 mortgage with a 25-year amortization at 4.59% (a typical 5-year fixed rate) would have an estimated monthly payment of $2,809.97. The same mortgage at 3.45% (a typical 5-year variable rate) would have an estimated monthly payment of $2,556.49. These are estimates and do not include CMHC insurance premiums (if applicable), property taxes, or other fees. For more information on mortgage insurance, visit CMHC.
Conclusion: Making the Right Choice for You
The difference between fixed and variable rate mortgage payments is a critical factor in your homeownership journey. Fixed rates offer a predictable path, making budgeting easier, while variable rates present the potential for lower initial costs and savings if rates fall, albeit with increased risk. As a Quebec mortgage brokerage, TiTaux.ca is dedicated to helping you navigate these complexities. We analyze your unique financial situation, discuss your comfort level with risk, and explore the current Quebec mortgage landscape to find the mortgage that best suits your needs.
Ready to explore your options or need help understanding your mortgage payment differences? Visit our contact page or learn more about the home purchase process on our site. If you're nearing your mortgage renewal, our renewal resources can provide valuable guidance. For more insights into the Canadian mortgage market, explore our blog.
Mots-clés :